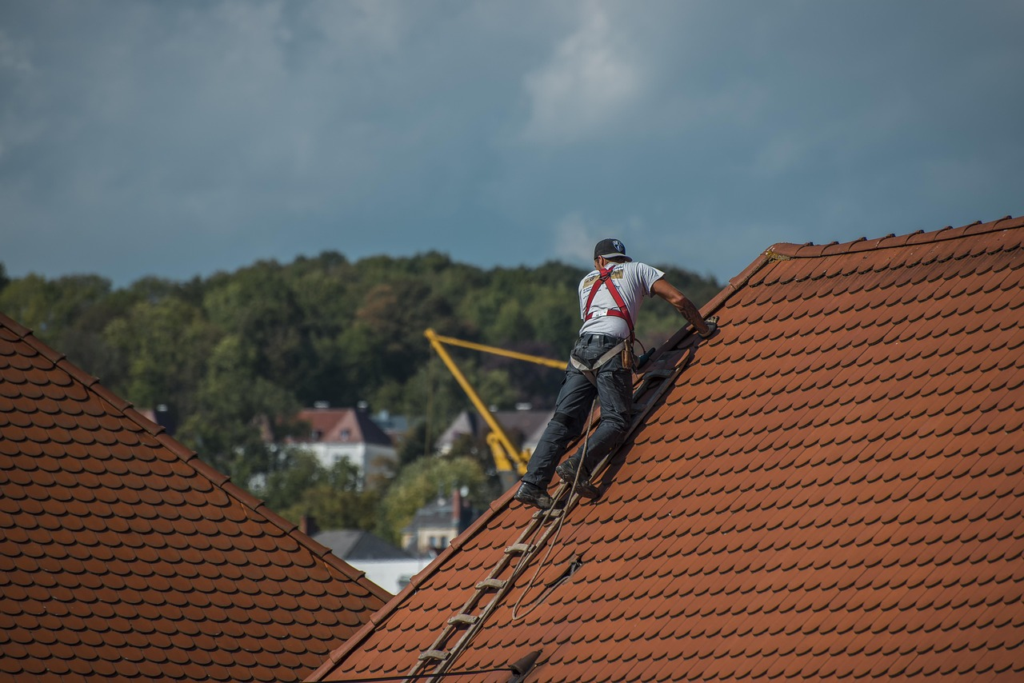
A roofing supplement is a request for the insurance company to review and revise an existing claim estimate, because the original scope doesn’t account for all the work needed to complete the covered repairs.
The request might involve missing materials, wrong quantities, extra damage, building-code requirements, or other necessary work the first estimate left out. For example, an adjuster’s estimate might include the shingles but leave out a needed roofing part that you found during your inspection. Your supplement would explain the gap and give evidence for the added work.
A supplement isn’t an automatic payment request, and it isn’t a way to raise the contract price just because your estimate is higher. Every item needs a legitimate basis, and the insurer makes coverage and payment decisions under the policy and the applicable rules.
When Should Roofers Submit an Insurance Supplement?
Supplements can add real money to a job, but only when the work is truly missing from the estimate. Compare the insurance estimate with your inspection findings and proposed scope before you assume the original allowance covers the whole project. Several situations may call for a closer look.
- Missing line items: The estimate may leave out parts needed for the documented repair, like starter shingles, ridge parts, flashing, or drip edge.
- Wrong quantities: The carrier’s measurements may not match the actual roof or the quantities needed to finish the work.
- Extra damage: A closer inspection or tear-off may reveal damaged decking or other conditions that weren’t visible at the first inspection.
- Code-related requirements: Building codes may require specific materials or install methods. Whether those costs are covered depends on the policy and the situation.
- Material or install requirements: Manufacturer instructions or the roof’s real conditions may call for extra work to install it properly.
- Pricing differences: The estimate may use a different price list, leave out a labor item, or miss a documented job condition.
The difference matters: a gap between your estimate and the carrier’s doesn’t automatically mean the carrier’s scope is incomplete. You need to identify what’s missing, explain why it’s necessary, and back it up with documents.
How to Prepare a Roofing Insurance Supplement
A strong supplement starts with the inspection, not with a request for more money. Your team should gather enough info to explain the work before you send a revised estimate.
1. Document the Roof Thoroughly
Take photos that show both the overall condition of the roof and the specific areas tied to the proposed work. Wide shots give context, and close-ups show individual parts and damage.
Record measurements, roof sections, material types, and existing conditions that matter. If you find damaged decking or other hidden problems during tear-off, photograph them before covering or removing the evidence whenever you can. Your documentation should make it easy for someone who has never been to the property to understand what you found.
2. Compare the Carrier’s Estimate With Your Scope
Review the carrier’s estimate line by line against your inspection notes, measurements, and proposed work. Look for missing parts, wrong quantities, and differences in labor or install requirements.
Don’t send a revised estimate that just lists everything your company normally includes in a roof replacement. Explain why each added item applies to this property. If you’re asking for more quantity, show how you calculated it. If you’re asking for a code-related item, point to the requirement and confirm that it applies to the project.
3. Build an Organized Supplement Package
A supplement should be easy to review. Organize the supporting info so each requested change connects to a specific piece of evidence. A typical package may include:
- The original carrier estimate and your revised estimate.
- A summary of the requested changes and the reason for each one.
- Photos labeled by roof section or part.
- Roof measurements, diagrams, and quantity calculations.
- Building-code references, where they apply.
- Manufacturer install instructions when they support the proposed work.
- Documentation of added conditions found during production.
Estimating platforms like Xactimate can help organize line items and pricing. But using a certain platform doesn’t make an estimate accurate by itself. The quantities, descriptions, pricing assumptions, and supporting evidence still have to be right.
4. Submit the Documentation and Track the Response
Follow the insurer’s process for receiving estimates and supporting documents. Keep a copy of what you sent, record the submission date, and track any response or request for more info.
If the insurer asks for clarification, answer the specific issue instead of sending the same package again. A missing measurement calls for a measurement. A disagreement about a particular install requirement calls for documents that address that requirement.
Keep the property owner informed about the status of the project and any decisions that affect the work. Don’t promise a specific approval amount or completion date while a supplement is still under review.
Should You Hire an Insurance Supplementing Company?
Preparing supplements in-house gives you direct control over documentation and communication, but it also takes time away from inspections, sales, and production. As your insurance restoration workload grows, your team may not be able to keep up with every estimate review, revision, and follow-up.
An insurance supplementing company can provide outside estimating and administrative support. Depending on the provider, its services may include reviewing the original estimate, finding possible scope gaps, preparing Xactimate or Symbility estimates, organizing supporting documents, and tracking supplement submissions.
Some companies only provide estimating. Others offer broader administrative support and communicate with insurers as part of their service. Those are different arrangements, so know exactly what you’re paying for before you hand over a claim file.
What Does an Insurance Supplementing Company Actually Do?
The scope of service varies, but a provider may help with several parts of the process:
- Estimate review: Compares the carrier’s estimate with your inspection findings and proposed scope.
- Supplement preparation: Builds an itemized estimate that explains the requested additions or corrections.
- Documentation organization: Arranges photos, measurements, code references, and other supporting material.
- Submission support: Helps prepare or submit the documents through the right process.
- Follow-up and revisions: Tracks responses, spots open questions, and prepares revisions when more info is needed.
The right service depends on where your team loses the most time. If your estimators can prepare accurate supplements but struggle to keep up with follow-ups, you may not need a full-service provider. If your team lacks estimating capacity, a company that handles estimate preparation may be more useful.
Do Roofers REALLY Need SuppTrax – Remko Bloemhard
When It Makes Sense to Bring in Supplement Specialists
At a certain volume, roofing insurance supplements stop being extra paperwork and become a full operational workload. That’s usually when contractors look for outside support, not because they can’t handle supplements, but because their time is better spent selling jobs, managing crews, and growing revenue.
One option is ClaimTrax, run by Remko Bloemhard, which focuses on insurance supplement workflows for contractors. The idea is to keep supplements moving while roofers stay focused on production and sales. For companies with steady insurance volume, that split can free up hours every week and keep claims from going cold.
Another option is Contractor Supplement Solutions, which provides dedicated supplement support for roofing contractors. Its site says the team audits the initial estimate and scope, researches the relevant building codes, documents what was missed, sends the updated scope to the carrier, and tracks the status and follow-up.
How to Choose the Right Insurance Supplementing Company
Don’t choose a provider based on promises about how much extra money it can recover. A legitimate supplement depends on the facts of the claim, the policy, and the supporting documents. Instead, look at the company’s actual process.
1. Check its roofing and restoration experience.
Roofing estimates involve specific materials, install requirements, measurements, and labor. Ask whether the company regularly handles roofing claims and whether its estimators understand the difference between a missing line item and one that just doesn’t apply to the job.
2. Ask who prepares and reviews the estimates.
Find out whether the work is done by in-house estimators, independent contractors, or other specialists. Ask about their experience with Xactimate or Symbility and how they verify measurements, quantities, and local requirements. If the provider offers services that involve claim adjustment or representation, verify the licensing and legal authority that apply.
3. Understand exactly what the service includes.
One company may give you an estimate and send the file back to your team. Another may handle submissions, responses, and follow-ups. Get the service scope in writing so you know which tasks are still yours.
4. Review the pricing structure.
Supplementing providers may charge a flat fee, a fee per file, or a percentage tied to an increase in the approved estimate. Some price estimate-only work and ongoing claim support differently.
Compare the total cost with the time your team would otherwise spend on the work. Ask when fees are due, what happens if a supplement is denied, and whether revisions or extra submissions cost more. Don’t assume a percentage-based deal is automatically the better one.
5. Look at communication and reporting.
You need to know which files are being reviewed, what’s been submitted, which claims need more documents, and where responses are still open. Ask whether the company gives regular status updates and whether your team can see them without chasing someone down.
6. Be careful with guaranteed results.
No supplementing company can guarantee that an insurer will approve every requested item or raise every estimate. Be wary of providers that promise specific recovery amounts without reviewing the claim or that encourage you to submit unsupported charges. A good provider should be able to explain its reasoning and show you the documents behind its recommendations.
In-House Supplementing vs. Outsourcing: Which Makes More Sense?
| In-house supplementing | Outsourced supplementing | |
| Control | Your team manages the whole workflow | You rely on the provider for the agreed services |
| Staffing | Needs trained internal staff | Adds outside estimating or admin capacity |
| Cost | Salaries, training, software, and time | Provider fees based on its pricing model |
| Communication | Direct control over homeowner and claim updates | Needs coordination between your team and the provider |
| Best fit | Companies with steady volume and in-house expertise | Companies that need extra capacity or specialized support |
Common Roofing Supplement Mistakes to Avoid
Even a well-meant supplement can cause delays or disputes if your team handles it poorly.
- Submitting unsupported line items: Every requested item should connect clearly to the property’s condition, necessary work, or an applicable requirement.
- Using inaccurate measurements: Wrong quantities weaken the whole estimate. Verify measurements instead of relying on rough guesses.
- Treating code upgrades as automatic coverage: A building-code requirement and an insurance coverage obligation aren’t the same thing. Check the policy and local requirements.
- Assuming overhead and profit always apply: General contractor overhead and profit should be supported by the project’s circumstances and applicable estimating practices. Don’t add them automatically as a guaranteed percentage.
- Waiting until the end of production to document extra damage: Record hidden conditions as soon as you find them, before the evidence is covered or removed.
- Ignoring follow-ups: An unanswered request for info or an untracked submission can leave a project stalled. Assign someone to check on open files.
- Making promises about insurance payments: Explain what your estimate includes and what documents you’ve submitted, and let the insurer make the coverage and payment decisions.
There’s also an important legal line to understand. Contractors can generally prepare estimates and explain the technical details of their proposed repair work, but negotiating a policyholder’s claim or advising on coverage may require a public adjuster license. The rules vary by state. Texas, for example, doesn’t allow a roofer or contractor to act as a public adjuster on a property where they’re also doing the work, and says contractors can’t advertise that they will. Check your state’s requirements before you decide what your employees or an outside supplementing company can do. Start with the Texas Department of Insurance guidance on roofing and insurance, and ask your attorney about your own state.
Build a Supplement Process Your Team Can Stand Behind
Roofing insurance supplements are part of managing restoration work responsibly. Your job is to document the real repair requirements, prepare accurate estimates, and keep property owners informed while the insurer reviews the claim. If your team needs more estimating or admin capacity, an experienced insurance supplementing company can help, as long as its services, fees, and legal responsibilities are clear. Build a communication-first process with ProLine, keep every customer conversation organized, and give your team more room to focus on delivering quality work and selling more jobs.
FAQs
What’s the purpose of a roofing insurance supplement?
A roofing supplement asks the insurer to review an existing estimate when documented damage or necessary repair work is missing, undercounted, or not accurately represented. The insurer reviews the supporting info and decides whether to revise its estimate or payment.
How long does a roofing insurance supplement take?
There’s no universal turnaround time. The review can depend on the insurer, how complex the requested changes are, the quality of your documents, and whether more info or inspections are needed. Track each submission and follow up through the right channel.
Do roofers need an insurance supplementing company?
No. Roofing contractors can prepare estimates and supporting documents themselves, as long as they stay within the legal limits that apply in their state. An outside supplementing company can help when your team needs more estimating or admin capacity.
How much does an insurance supplementing company charge?
Pricing varies by provider and service. Some charge a flat fee or per-estimate rate, while others charge a percentage tied to an increase in the approved estimate. Compare the fee, included services, revision policy, and payment terms before you sign an agreement.